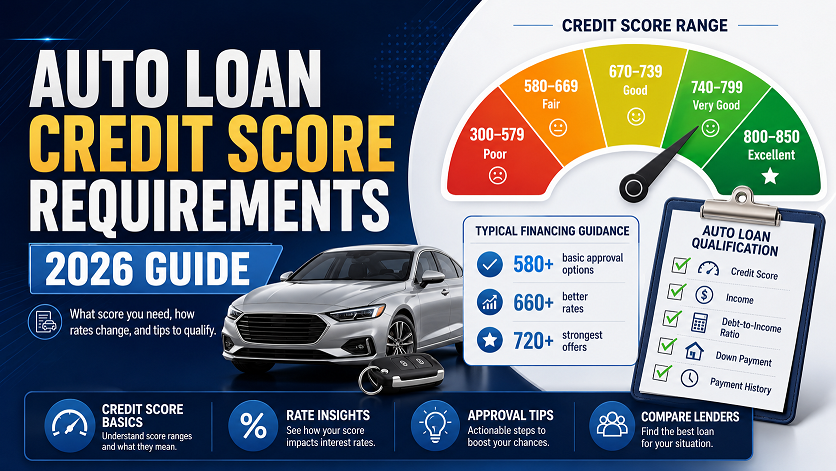
There is no universal minimum credit score for an auto loan. Banks, credit unions, finance companies and dealers use different underwriting standards. A higher score can improve the chance of receiving a lower APR, but lenders also consider income, debts, down payment, loan amount, term, vehicle value, age and mileage. Experian reported Q1 2026 average APRs of 6.39% for new vehicles and 11.43% for used vehicles; these are market averages, not rates guaranteed at a particular score.
A vehicle buyer can qualify for financing across a wide range of credit profiles, but approval is only the first question. The more important questions are: What is the out-the-door price? How much is financed? What is the APR? How long is the term? Which optional products were added? And will the vehicle remain reliable after the loan is paid off?
This guide explains auto-loan score requirements and cost using a dated methodology. It does not rank lenders based on teaser rates or promise approval at a particular score.
The lender reviews repayment history, current debts and documented ability to make the payment.
Price, book value, age, mileage and down payment affect collateral risk.
A low monthly payment can hide a long term, higher interest and negative-equity risk.
What credit score is needed for an auto loan?
Auto lending does not have a government minimum comparable to FHA mortgage score tiers. Each lender sets its own credit policy, and some specialize in prime borrowers while others serve subprime applicants. The score model can also vary. A consumer score displayed by a banking app may not equal the automotive score or bureau data used by the lender.
| Credit profile | Likely market experience | Ways to reduce risk and cost | Main danger |
|---|---|---|---|
| Very strong credit | Broader lender choice and possible promotional manufacturer financing | Compare rebate versus promotional APR and keep the term reasonable | Overpaying for the vehicle because financing appears cheap. |
| Good credit | Competitive bank, credit-union, captive-finance and dealer options | Use a preapproval to negotiate rate and price separately | Assuming the first dealer offer is the lowest available. |
| Fair credit | Approval may be available at higher APR or with a smaller loan | Larger down payment, less expensive vehicle and shorter affordable term | Focusing only on monthly payment and accepting add-ons. |
| Poor or thin credit | Fewer options; high-rate or specialized financing may be offered | Check credit unions, document income, use a qualified co-borrower only when appropriate | Unaffordable loan, yo-yo financing, buy-here-pay-here terms or repeated repossession risk. |
Score bands are useful for market analysis, but they are not lender promises. Two borrowers with the same score can receive different offers because one finances an older used car with high LTV while the other makes a substantial down payment on a new vehicle.
Which score model do auto lenders use?
A lender may use a base FICO score, an industry-specific FICO Auto Score, VantageScore or a proprietary model. It may pull one bureau or more than one. Ask which bureau and score type were used if the application is declined or priced unexpectedly. An adverse-action notice should identify key reasons and the credit-report source when applicable.
Check all three reports at AnnualCreditReport.com before shopping. If information is wrong, use the documented steps in how to fix credit-report errors.
Current 2026 auto-loan rate benchmarks
Data methodology
Market figures below use Experian’s Q1 2026 State of the Automotive Finance Market reporting and the Federal Reserve G.19 release available in August 2026. Experian’s figures reflect financed transactions in its dataset; Federal Reserve figures cover specified commercial-bank new-car products. Neither source predicts an individual offer. This section should be reviewed quarterly and updated when a newer complete dataset is available.
| Benchmark | Reported APR | Vehicle/term | Reporting period | Correct interpretation |
|---|---|---|---|---|
| Experian overall average | 6.39% | New vehicles; terms mixed | Q1 2026 | Market average across financed new-vehicle transactions—not a prime offer. |
| Experian overall average | 11.43% | Used vehicles; terms mixed | Q1 2026 | Used loans generally price higher because vehicle and borrower mixes differ. |
| Federal Reserve commercial banks | 7.14% | 60-month new-car loans | Latest displayed 2026 observation in the August release | Bank-product average; excludes many dealer, credit-union and used-car loans. |
| Federal Reserve commercial banks | 6.97% | 72-month new-car loans | Latest displayed 2026 observation in the August release | Do not infer that a longer term is cheaper overall; borrower and product mixes differ. |
Experian’s published July 2026 analysis also showed a wide spread by credit tier: averages for top-tier new-car borrowers began around 4.55%, while the poorest-credit tier averaged about 16.01%. For used vehicles, the range was about 6.30% to 21.77%. These describe groups of funded loans—not minimum, maximum or guaranteed rates.
Do not compare APRs without matching assumptions
A new-car manufacturer promotion, a used-car credit-union loan and a dealer-arranged subprime contract are different products. Match vehicle status, amount financed, term, down payment, fees and application date.
What determines your auto-loan APR and approval?
The CFPB identifies credit history, income and debts, loan amount, loan term, down payment, and new-versus-used status as important pricing factors. Lenders may also consider:
- vehicle age, mileage and book value;
- dealer versus private-party purchase;
- residence, employment and income stability;
- prior auto-loan payment and repossession history;
- loan-to-value ratio and negative equity from a trade-in;
- co-borrower or co-signer profile;
- automatic-payment or membership discounts; and
- lender, state and dealer program rules.
Dealer financing can include a markup
A dealer may submit the application to one or more lenders and receive a “buy rate.” The retail contract rate offered to the buyer can be higher. The CFPB states that auto-loan interest rates are negotiable and dealers might not offer the lowest rate for which the consumer qualifies. A bank or credit-union preapproval creates a comparison point.
Manufacturer promotional financing
Captive finance companies sometimes offer low or 0% APR promotions to highly qualified buyers on selected new vehicles. The buyer may have to choose between promotional financing and a cash rebate. Compare the amount financed, total interest and lost rebate. A 0% promotion does not make an overpriced vehicle affordable.
New versus used auto financing
New vehicles often qualify for lower APRs because collateral is newer, manufacturer incentives may apply and values are easier to establish. They also usually cost more and can depreciate rapidly.
Used vehicles often have higher APRs, especially when older or high-mileage. The purchase price may be lower, but repair risk is greater. Some lenders restrict vehicle age, mileage, title type or minimum loan amount.
| Factor | New vehicle | Used vehicle | What to compare |
|---|---|---|---|
| APR | Often lower; promotions possible | Often higher | Actual approved APR after rebate choices |
| Price | Usually higher | Usually lower | Out-the-door price, not sticker price |
| Depreciation | Can be rapid early | Earlier owner absorbed some decline | Loan balance versus future vehicle value |
| Maintenance | Warranty may reduce early repair costs | More inspection and repair risk | Independent inspection and service history |
| Loan term | Long terms more available | May be limited by age/mileage | Whether loan outlasts useful ownership period |
How APR changes payment and total interest
The payment on a fixed-rate installment loan depends on principal, periodic interest rate and number of payments:
In the formula, P is the amount financed, r is the monthly interest rate and n is the number of monthly payments. Taxes, registration, add-ons and negative equity increase P when financed.
Consider a hypothetical $30,000 amount financed for 60 months:
| APR | Approximate payment | Approximate total interest | Dataset connection |
|---|---|---|---|
| 6.39% | $585.44 | $5,126 | Experian Q1 2026 overall new-loan average |
| 11.43% | $658.72 | $9,523 | Experian Q1 2026 overall used-loan average |
| 16.01% | $729.70 | $13,782 | Experian poor-tier new-loan average cited in July 2026 analysis |
| 21.77% | $824.65 | $19,478 | Experian poor-tier used-loan average cited in July 2026 analysis |
These calculations assume a fixed APR, no fees outside the principal and exactly 60 payments. They illustrate cost sensitivity; they are not loan quotes. The vehicle, term and borrower mix behind market averages varies.
Why extending the term can be dangerous
A 72- or 84-month loan can reduce the required payment while increasing total interest and the time spent owing more than the car is worth. Experian reported that roughly one in three financed vehicle loans exceeded 72 months in Q2 2026. A long term may also remain after warranty coverage ends.
Compare at least two term options and ask for total of payments. Choose a payment the budget can support without relying on an excessively long loan.
Down payment, trade-in and auto-loan LTV
Auto loan-to-value compares the amount financed with the vehicle’s actual cash value:
If a vehicle is worth $25,000 and the buyer finances $27,500 after taxes, fees and add-ons, the starting LTV is 110%. A lender may permit that level, but the borrower begins with negative equity.
A down payment reduces the loan amount, payment and interest. It can also make approval easier when the credit profile is weaker. Keep emergency savings and money for insurance, registration, maintenance and repairs; a down payment should not leave the household without a cushion.
Trading a vehicle with negative equity
When the trade payoff exceeds its value, the difference may be rolled into the new loan. That raises the amount financed without increasing the new vehicle’s value. Ask for four numbers separately: new-vehicle price, trade value, old-loan payoff and negative equity. Consider delaying the trade or paying down the balance.
How to shop for an auto loan
Set an all-in vehicle budget
Include insurance, fuel or charging, taxes, registration, maintenance and repairs—not only the loan payment.
Check credit reports
Correct factual errors and understand adverse history before a lender or dealer frames the discussion.
Get direct preapprovals
Compare banks, credit unions and reputable online lenders for the same vehicle status, amount and term.
Negotiate the out-the-door price
Separate vehicle price from financing, trade-in and optional products. Request a written itemization.
Let the dealer compete
Show or describe the preapproval terms and ask whether dealer-arranged financing can beat the APR and total cost.
Reject unwanted add-ons
Service contracts, GAP products, etching, coatings and maintenance plans are not automatically required. Ask the cash price and financing impact of each.
Read the retail installment contract
Verify APR, finance charge, amount financed, total of payments, term, payment schedule and every product before signing.
Confirm financing is final
Do not assume a conditional delivery is permanent. Understand whether the dealer can require a return or offer different terms if financing is not approved.
FTC warning on deceptive pricing
In March 2026, the FTC warned 97 dealership groups about advertising practices involving low prices followed by mandatory fees. Preserve advertisements, request the complete out-the-door price in writing and review every add-on.
Auto loans with fair or poor credit
A high-cost auto loan can become a financial trap when the vehicle is essential for work. Improve the transaction rather than focusing only on approval:
- choose a reliable, less expensive vehicle;
- make a documented down payment without draining savings;
- use a qualified co-borrower only when both parties understand full legal responsibility;
- compare credit-union and community-bank programs;
- avoid financing unnecessary dealer products;
- select the shortest term with an affordable payment; and
- ask whether refinancing later carries title or prepayment restrictions.
Buy-here-pay-here dealers may approve borrowers rejected elsewhere, but interest, pricing, payment frequency, tracking devices and repossession practices require careful review. Verify licensing and obtain the complete contract before paying a deposit.
Should you use a personal loan to buy a car?
An unsecured personal loan may avoid a vehicle lien, but it can carry a higher APR and shorter term. Some lenders restrict vehicle purchases or require direct payoff. Compare the auto loan with the options in personal loans with a 580 credit score, using the same amount and term.
Refinancing an existing auto loan
Refinancing may help when credit has improved, market rates are lower or the original dealer rate was uncompetitive. Compare payoff amount, new APR, remaining term, title fees and total interest from today forward. Extending the term can reduce the payment while increasing total cost.
Frequently asked questions
What credit score is needed for a car loan?
No universal score is required. Lender, vehicle, income, down payment, LTV and credit-history rules vary. Approval is possible across many score ranges at very different costs.
Can I get an auto loan with a 600 score?
Possibly. Expect offers to vary widely. A lower-priced vehicle, larger down payment, stable income and direct lender preapproval can improve the transaction, but nothing guarantees approval.
What is a good credit score to buy a car?
A good or better score generally expands lender choice and may reduce APR, but the vehicle, term, down payment and complete report still matter.
Are used-car loan rates higher?
They often are. Experian reported Q1 2026 averages of 11.43% for used vehicles and 6.39% for new vehicles. Individual offers can differ.
Does auto-loan shopping hurt credit?
Applications can create hard inquiries. Credit-scoring models commonly group certain rate-shopping inquiries within a defined window, but the window varies by model. Keep shopping focused.
Can the dealer change my interest rate?
Dealer-arranged financing may include a markup above the lender’s buy rate. Rate is negotiable. Conditional financing can also change if final approval is not obtained, so confirm the contract status.
Is 0% financing always the best deal?
No. It may require strong credit and can replace a cash rebate. Compare vehicle price, rebate, amount financed and total cost under both choices.
How much should I put down?
Enough to control LTV and payment without eliminating emergency savings. The right amount depends on vehicle value, trade equity, APR and budget.
Is an 84-month auto loan a bad idea?
It increases the chance of prolonged negative equity and paying interest after the vehicle ages substantially. Compare total interest and likely ownership period.
Can I remove dealer add-ons after signing?
Cancellation rights depend on the product and contract. Some refunds may go to the loan balance rather than the borrower. Prevent the problem by reviewing every item before signing.
The bottom line
Auto loans do not have one required credit score. Credit influences APR and available lenders, but income, debts, down payment, vehicle value, term and loan-to-value can be equally important to approval and cost.
Use current market data as a benchmark, not a promise. Obtain direct preapprovals, negotiate the vehicle’s out-the-door price separately, compare APR and total of payments, remove unwanted add-ons and choose a term that does not outlast the vehicle or budget.
Related credit and loan guides
Data and consumer-protection sources
- Experian Automotive: State of the Automotive Finance Market
- Experian: Q1 2026 new and used auto-loan averages
- Federal Reserve: G.19 Consumer Credit and auto-loan terms
- CFPB: Auto-loan shopping resources
- CFPB: Factors determining an auto-loan rate
- CFPB: Negotiating dealer-arranged financing
- FTC: Financing or leasing a car
- FTC: 2026 warning about deceptive dealer pricing
- AnnualCreditReport.com: Federally authorized credit-report access
3 thoughts on “Auto Loan Credit Score Requirements 2026: Rates and Approval”