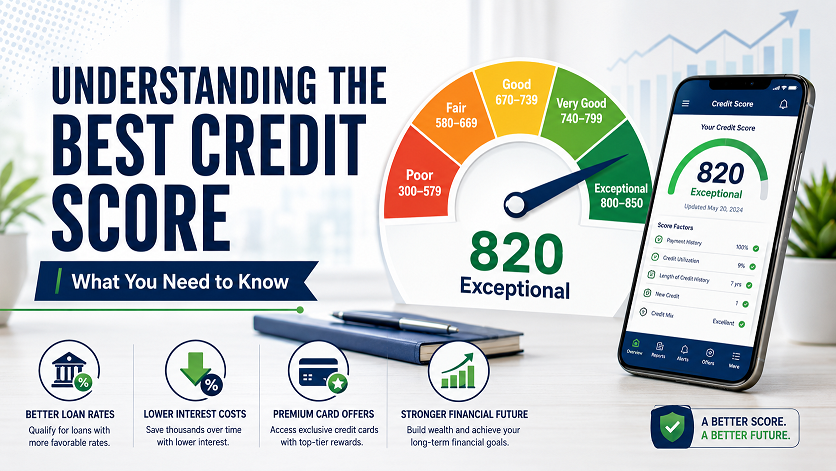
The highest possible credit score depends on the scoring model. For the base FICO Scores and VantageScore credit scores most consumers recognize, the maximum is 850. Some industry-specific FICO Scores used for credit-card and auto lending range from 250 to 900. A 900 in one of those specialized models is not “better than” an 850 base score; the numbers come from different scales.
Editorial review: Score-model and statistical information was checked against FICO, VantageScore, Experian and Consumer Financial Protection Bureau resources on August 30, 2026. Product eligibility and pricing remain lender-specific.
What is the highest credit score possible?
The answer is 850 when the number is a base FICO Score or a VantageScore. Both brands use a 300–850 range for their familiar general-risk scores. The score is a statistical prediction based on information in a credit report, not a grade of someone’s character, income or wealth.
“Perfect credit score” is an informal phrase for the top number in a particular model. It does not mean a credit report is permanently perfect, that every lender sees the same number, or that an application will be approved. Scores can differ because the lender selects another model, obtains data from another bureau or calculates the score on a different date.
A consumer may simultaneously have an 850 from one combination of model and bureau and a lower number from another. That is normal. Equifax, Experian and TransUnion maintain separate files, while FICO and VantageScore build scoring models that evaluate report data. The bureau and scoring model perform different jobs.
Why do some credit scores go to 900?
FICO publishes two broad families of scores. Base FICO Scores generally range from 300 to 850 and estimate overall credit risk. Industry-specific FICO Scores range from 250 to 900 and are tailored for certain types of lending, including auto and credit-card decisions.
| Score type | Published range | Typical purpose | Maximum |
|---|---|---|---|
| Base FICO Score | 300–850 | General credit-risk assessment | 850 |
| VantageScore | 300–850 | General credit-risk assessment | 850 |
| Industry-specific FICO Score | 250–900 | Auto lending or bankcard decisions, depending on version | 900 |
Do not convert one scale into another using a percentage. An 810 base FICO Score and an 810 auto-enhanced FICO Score are not necessarily equivalent risk assessments. Record the full model name, bureau source and date whenever you compare scores.
Where does 850 fit on the credit-score chart?
FICO’s consumer guidance places base scores from 800 to 850 in its Exceptional band. An 850 sits at the top of that band; it is not a separate lender-defined approval category.
VantageScore 4.0 uses different category boundaries. Its highest published tier is Superprime, covering 781–850. Because the brands use different labels, do not apply FICO’s “Exceptional” boundary to a VantageScore without identifying the model.
For a complete side-by-side reference, use the 2026 credit score chart. The chart page owns the range comparison; this article focuses specifically on maximum scores and whether pursuing one is useful.
How rare is an 850 credit score in 2026?
Experian’s analysis of its consumer credit data reported that 1.71% of U.S. consumers with a FICO Score had an 850 as of June 2026—roughly one out of 58. That figure has a specific source, model brand and measurement date. It should not be treated as a permanent nationwide constant or mixed with statistics based on VantageScore.
The same analysis found that perfect scorers generally shared long-established credit habits: they avoided missed payments, used a small portion of available revolving credit and maintained accounts over many years. These are associations within the analyzed group, not a formula that promises an 850.
Rarity also does not create a special financial prize. A lender may group a broad range of very strong applicants into the same pricing tier. Another lender may use a different cutoff, score model or underwriting system. The practical value of moving from a weak profile to a strong one can be meaningful; the incremental value of moving from an already-exceptional score to exactly 850 may be limited.
Do you need an 850 to get the best loan or credit card?
No universal rule says an applicant must have an 850 to receive a lender’s best terms. Creditors establish their own eligibility, pricing and credit-limit policies. Some divide applicants into score tiers, while others combine a score with data such as income, debt-to-income ratio, requested amount, loan-to-value ratio, account history and collateral.
A score that qualifies for a strong tier at one lender may fall into another tier elsewhere. Rates also respond to market conditions, loan term, down payment, points, fees and product structure. This is why claims such as “760 always gets the same rate as 850” are too broad unless tied to a named creditor, product and date.
| Application | Credit is only one part | Costs to compare |
|---|---|---|
| Mortgage | Loan program, DTI, down payment, property and reserves may matter | Interest rate, APR, points, closing costs, mortgage insurance and total payment |
| Auto loan | Vehicle, term, down payment, income and lender policy may matter | APR, amount financed, term, add-ons and total interest |
| Credit card | Income, existing exposure, recent accounts and issuer policy may matter | APR, annual fee, rewards rules, penalty terms and foreign-transaction fee |
| Personal loan | Income, DTI, amount, term and lender model may matter | APR, origination fee, monthly payment and total repayment |
Prequalification with a soft inquiry can help compare potential offers when available, but it is not final approval. A formal application can involve a hard inquiry and additional verification. Read current terms directly from the lender rather than relying on an independent article’s claimed approval cutoff.
What helps create a very high credit score?
FICO does not disclose a simple checklist that guarantees 850. Its published educational framework identifies payment history, amounts owed, length of credit history, new credit and credit mix as major categories for base scores. Their influence can vary with the information in an individual file, and another model may evaluate the data differently.
Consistent on-time payment history
Pay at least the amount due by every deadline. A single serious delinquency can remain relevant long after the immediate bill is resolved. Automatic payments and calendar alerts can reduce accidental misses, but account holders should still verify that payments cleared.
Low revolving utilization
Utilization compares reported card balances with credit limits. Lower reported use is generally less risky than repeatedly approaching limits, but “always carry a balance” is a myth. Paying interest does not build a score. Statement balances can usually be paid in full while accounts still report activity.
Established accounts
Older well-managed accounts can support a mature file. Do not keep an expensive card solely because it is old without evaluating the fee and alternatives. Closing an account can affect available credit and eventually account-age calculations, but the financial cost still matters.
Measured new-credit activity
Frequent applications can create hard inquiries and new accounts. Apply when a product serves a real need, not merely to chase a few points. Checking your own report or score is a soft inquiry and does not reduce the score.
Accurate credit reports
A scoring model can only evaluate the bureau data available to it. Review reports for accounts that are not yours, duplicate debts, incorrect late payments, wrong balances and identity-theft indicators. Dispute factual errors with supporting evidence; do not dispute accurate negative information simply because it is unfavorable.
A responsible plan for improving excellent credit
If the profile is already strong, protecting it is more useful than trying to manipulate the score every month. Scores naturally move as card balances report, accounts age and lenders update information.
Review all three reports
Use AnnualCreditReport.com, the federally authorized source, and verify identifying information, account ownership, balances and payment status.
Protect every due date
Set reminders or autopay for at least the minimum, maintain sufficient funds and confirm successful processing.
Manage reported balances
Pay revolving debt based on budget and interest cost. Avoid maximizing cards before a major application.
Limit unnecessary applications
Open an account because its benefits, cost and purpose fit—not because a score simulator suggests a guaranteed result.
Compare complete offers
Use APR, fees, term, monthly payment and total cost. A high score should support good decisions, not encourage extra borrowing.
How to protect an exceptional credit profile
Credit protection includes accuracy and security. Monitor statements for unfamiliar purchases, use unique passwords and multifactor authentication where offered, and respond promptly to breach notices. A credit freeze can restrict access to a bureau file and help prevent many new-account identity-theft attempts. Freezes must be managed separately with Equifax, Experian and TransUnion.
Do not confuse a freeze with a fraud alert or credit lock. The legal effect and management process can differ. The Federal Trade Commission’s IdentityTheft.gov provides a recovery plan when identity theft has occurred. Ordinary billing disagreements, debt validation and identity-theft blocking are separate processes, so use the procedure that matches the facts.
Keep contact details current with creditors, inspect paper and electronic notices, and preserve relevant records. An excellent score is not protection against fraud, billing mistakes or account takeover.
Using a high score for mortgages, auto loans and cards
Before a mortgage, auto loan or major credit-card application, avoid opening several unrelated accounts. Check reports early enough to address genuine errors and gather documents the lender may request. Ask about prequalification and compare multiple offers within appropriate rate-shopping windows where applicable.
For mortgages, the CFPB recommends reviewing multiple Loan Estimates. For auto financing, compare bank or credit-union preapproval with dealer-arranged financing and review the final amount financed. For rewards cards, calculate whether the annual fee is justified by benefits you will actually use. A high credit score does not make an expensive product inexpensive.
Readers preparing for a specific product can use the mortgage credit-score guide, auto-loan credit requirements and credit-card comparison methodology. These pages explain product-specific decisions without pretending one score controls every outcome.
Perfect credit-score myths to avoid
| Myth | Reality |
|---|---|
| You must carry a balance and pay interest | Carrying interest-bearing debt is not required to show card activity or build credit. |
| An 850 guarantees approval | Lenders use additional eligibility and underwriting information, and each sets its own policies. |
| All three bureaus calculate one score | Bureaus maintain reports; scoring companies and lender models calculate scores from selected data. |
| A 900 score is always better than 850 | They may be maxima on different score scales and cannot be compared as one ladder. |
| Checking your own credit lowers it | Consumer self-checks are soft inquiries and do not reduce the score. |
| A credit-repair company can guarantee 850 | No legitimate service controls scoring models or can guarantee removal of accurate information or a specific result. |
Frequently asked questions
Is 850 the highest credit score?
Yes for base FICO Scores and VantageScore credit scores. Some industry-specific FICO versions range to 900.
Can a credit score be higher than 850?
It can in a model whose published scale extends above 850, such as certain industry-specific FICO Scores. The model name must accompany the number.
How many people have an 850 credit score?
Experian reported 1.71% of U.S. consumers with a FICO Score had an 850 as of June 2026. This dated figure should not be generalized to every model or future period.
Is 800 considered a perfect credit score?
It is not the numerical maximum, but FICO places 800–850 in its Exceptional band. Many lending decisions do not require the exact maximum.
Is 900 a good credit score?
A 900 is the maximum on certain 250–900 industry-specific FICO scales. It is not a valid base FICO or VantageScore number.
Does income affect a credit score?
Income is not part of standard consumer credit reports used to calculate familiar FICO and VantageScore numbers, but lenders can consider income separately when evaluating repayment ability.
Does paying off every card create an 850?
No. Paying debt can improve finances, but score results depend on the full report, model, timing and how balances are reported.
Will closing a credit card ruin perfect credit?
Not necessarily. It can change available credit and utilization, while closed positive accounts may remain on reports for a time. Evaluate fees, limits and financial usefulness.
Can I get an 850 with a mortgage or other debt?
Yes, owing debt does not automatically prevent a maximum score. Payment history, balances and the overall file matter. Never borrow merely to chase points.
Why did an 850 score drop?
A changed reported card balance, new inquiry, new account, updated status or difference in model/bureau/date can move a score. A small change does not necessarily signal financial damage.
Can credit repair guarantee a perfect score?
No. Companies cannot guarantee an 850 or legally force removal of accurate, current information. Review credit-repair scam warning signs before paying a service.
Where can I check my credit reports?
AnnualCreditReport.com is the federally authorized source for reports from Equifax, Experian and TransUnion. A report does not always include the same score a lender will use.
Bottom line
The highest base FICO Score and VantageScore is 850. Certain industry-specific FICO models top out at 900, but their scale is different. A maximum score is possible, uncommon and unnecessary for many competitive offers.
A better objective is an accurate, mature and responsibly managed credit file combined with sound finances. Pay on time, control expensive revolving debt, review reports, protect personal information and compare the full cost of borrowing. Those habits are valuable even when the number moves below 850.
Related credit guides
Official and primary sources reviewed
- FICO: credit scores and base ranges
- FICO: base and industry-specific score versions
- VantageScore: VantageScore 4.0 range and tiers
- CFPB: what a credit score is
- CFPB: understanding multiple credit scores
- Experian: June 2026 analysis of consumers with 850 FICO Scores
- AnnualCreditReport.com: federally authorized credit reports
- FTC IdentityTheft.gov: identity-theft recovery
Educational disclosure: This article provides general U.S. consumer-credit education, not individualized financial, legal, tax or lending advice. Credit decisions, scores, rates and product terms vary by lender, model, bureau, location and applicant. No score, approval, rate, savings or timing is guaranteed. If affiliate links are added later, disclose that relationship clearly without changing rankings based on compensation.