A HELOC usually makes more sense when you want to preserve an existing low-rate first mortgage and borrow money in stages. A cash-out refinance may be more suitable when replacing the entire mortgage produces an acceptable fixed rate, one predictable payment and enough savings to justify refinancing costs. The correct choice depends on the old mortgage rate and remaining term, cash needed, HELOC variable-rate risk, refinance closing costs, credit profile, LTV/CLTV and how long you expect to keep the debt.
Both options turn home equity into debt secured by your property. The structural difference is decisive: a HELOC normally sits beside the first mortgage as a junior lien, while a cash-out refinance pays off the old mortgage and replaces it with a larger new first mortgage.
This article stays focused on that side-by-side decision. For minimum scores, CLTV formulas and lender-specific HELOC eligibility, use the dedicated HELOC credit requirements guide.
HELOC versus cash-out refinance: core differences
| Feature | HELOC | Cash-out refinance |
|---|---|---|
| What changes | Adds a revolving junior lien while preserving the first mortgage | Replaces the first mortgage with a larger new mortgage |
| How funds arrive | Draw as needed up to the available line during the draw period | Lump sum after paying off the old mortgage and eligible costs/liens |
| Rate structure | Usually variable; some plans allow fixed-rate balance conversions | Commonly fixed, though adjustable options exist |
| Payment structure | Separate first-mortgage and HELOC payments; some draw periods allow interest-only minimums | One new principal-and-interest mortgage payment |
| Closing costs | May be lower or lender-paid, sometimes subject to early-closure reimbursement | Often appraisal, title, lender, recording and other refinance costs |
| Best-known advantage | Preserves a favorable first-mortgage rate and only charges interest on drawn funds | Can lock the entire balance into one predictable fixed payment |
| Main risk | Variable payments, draw-period expiration and two liens | Reprices the entire old balance and may restart a long amortization term |
The CFPB describes a HELOC as reusable credit: repaying draws restores available capacity under the agreement. A cash-out refinance replaces the existing mortgage with a larger mortgage and distributes the difference, after payoff and transaction costs, as cash.
The old mortgage rate and remaining term are often more important than the rate on the new cash alone.
A HELOC fits staged expenses; cash-out refinancing funds the full amount at closing.
HELOC flexibility brings rate risk; a fixed refinance brings payment stability.
Credit-score requirements compared
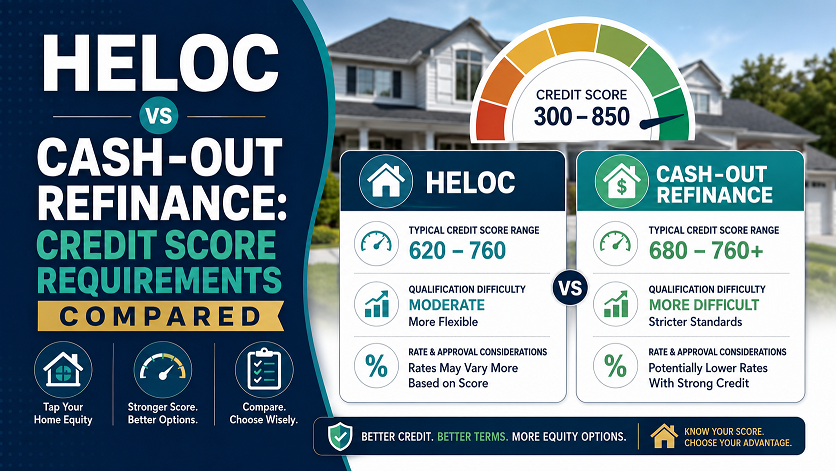
Neither product has one nationwide consumer score requirement. HELOC lenders set their own thresholds; two large banks currently publish 660 minimums for standard products, while credit unions and other lenders may differ. Score is evaluated with available equity, CLTV, DTI, income and property eligibility.
Cash-out refinance rules depend on the agency, automated-underwriting decision, transaction and lender overlay. Freddie Mac currently lists a 620 minimum Indicator Score for cash-out refinance unless its Guide specifies otherwise, with higher scores for certain high-LTV or property scenarios. Fannie Mae sends borrowers to its Eligibility Matrix and Selling Guide for LTV and manual score requirements; Desktop Underwriter evaluates the complete risk profile.
A score that passes a program rule does not guarantee approval or good pricing. Cash-out transactions can receive different loan-level pricing than purchase or limited-cash-out loans. A lender may require higher scores or lower LTV than agency eligibility.
Compare the score actually used
Ask for the credit-score model, representative-score method, underwriting system and lender overlay. A free-app score may not match the mortgage or HELOC score used for pricing.
Cost example: preserving a low-rate mortgage
This illustration demonstrates mechanics, not current market pricing. It uses hypothetical rates so readers can reproduce the calculation. Actual HELOC and refinance offers may be higher or lower, and the options can have different fees, insurance and underwriting results.
| Illustrative measurement | HELOC path | Cash-out refinance path |
|---|---|---|
| First mortgage | Keep $250,000 at 3.75%; estimated P&I $1,285.33 | Replace it within a new $325,000 balance at 6.75% |
| New cash borrowed | $75,000 drawn from HELOC | $75,000 included in new mortgage before financed costs |
| Initial monthly debt payment | $1,285.33 + $531.25 interest-only HELOC = $1,816.58 | $2,107.94 principal and interest |
| HELOC repayment-period estimate | $650.87 for the HELOC if $75,000 amortizes over 20 years at unchanged 8.50%; combined $1,936.20 | Not applicable; new mortgage remains $2,107.94 under fixed assumptions |
| Illustrative closing costs | $1,000 | $9,750 |
| Major uncertainty | HELOC rate and payment can rise; first mortgage ends five years earlier than the new refinance term | Old balance is repriced and amortization restarts over 30 years |
Under these assumptions, the HELOC path begins $291.36 lower per month and has $8,750 less assumed closing costs. That does not prove it is always cheaper. The HELOC rate could rise, the line may carry fees, and an interest-only minimum does not reduce principal. A cash-out refinance could become more attractive if the existing mortgage rate were close to or above the new refinance rate.
The comparison must also use the same time horizon. A 30-year refinance can lower a payment by stretching debt longer, while increasing lifetime interest. Compare total cost over the number of years you realistically expect to keep the loan, not only the first monthly payment.
HELOC variable-rate and repayment risk
HELOC APRs commonly equal an index, often prime, plus a lender margin. The rate can change even when you do not draw more money. Review the introductory period, index, margin, floor, periodic change limit and lifetime cap.
Some plans permit interest-only payments during the draw period. That creates a deceptively low minimum because the principal remains. When repayment begins, further draws stop and principal must amortize; the CFPB warns that payments are often significantly higher. Some agreements may require a large balance payment.
Rate stress test
For the $75,000 example, monthly interest-only cost at 8.50% is $531.25. At 10.50%, it would be $656.25; at 12.50%, $781.25. This simple calculation excludes fees and principal. If the household cannot handle the higher scenario, the requested line or draw may be too large.
A cash-out refinance with a fixed rate eliminates that variable-rate risk for the new first mortgage, but the borrower pays the fixed rate on the entire refinanced balance, including the old $250,000 in the example.
Closing costs, break-even and “no-cost” offers
Cash-out refinancing typically involves a new first-mortgage closing. Costs may include lender charges, appraisal, title work, recording, taxes or government fees and prepaid items. A lender-credit or “no-closing-cost” offer usually shifts cost into a higher rate, larger balance or early-payoff condition; it does not make the expense disappear.
HELOC lenders may waive or pay certain costs, but read early-closure reimbursement terms, annual fees, inactivity fees, fixed-conversion charges and appraisal conditions. CFPB rules require important disclosures about draw/repayment periods, fees, payment calculation and variable APR.
Simple break-even formula
Incremental upfront cost ÷ realistic monthly savings = approximate months to break even. Use savings after accounting for both loans, mortgage insurance and any scheduled payment changes. Do not use an interest-only HELOC payment as though it were equivalent to amortizing principal.
In the illustration, the cash-out refinance has $8,750 more assumed upfront cost and no monthly savings versus the initial HELOC path, so a traditional positive break-even does not occur under those assumptions. Changing the old mortgage rate, HELOC rate or loan term can reverse the result.
When a HELOC or cash-out refinance may fit
A HELOC may fit better when:
- Your existing first-mortgage rate is materially below current refinance offers.
- You need funds in phases for renovations, tuition timing or uncertain project invoices.
- You can repay draws aggressively and tolerate variable-rate increases.
- The verified HELOC fees and CLTV limit are acceptable.
- You expect to keep the first mortgage or pay off the line relatively quickly.
A cash-out refinance may fit better when:
- The new first-mortgage rate is competitive with or below the old mortgage rate.
- You need a known lump sum and value one fixed payment.
- The break-even period is shorter than the expected time in the home.
- The new term does not create unacceptable lifetime interest or delay payoff goals.
- Written Loan Estimates show that the refinance outperforms available HELOC terms.
Neither may fit when:
- The payment requires using retirement funds or eliminating emergency reserves.
- You are consolidating cards without a plan to prevent new balances.
- Income is unstable or the stress-tested payment is unaffordable.
- The purpose is discretionary spending that does not justify risking the home.
- A smaller unsecured loan, savings plan or project delay carries less total risk.
Your home secures both options
A lower rate does not remove foreclosure risk. Converting unsecured credit-card balances into home-secured debt can make the consequences of nonpayment more severe.
Tax treatment, lien position and future refinancing
Interest is not automatically deductible simply because a home secures the debt. IRS guidance generally requires qualifying proceeds to buy, build or substantially improve the home securing the loan, subject to itemizing and debt limits. Interest used for personal expenses or card consolidation generally does not qualify under the post-2017 rules. Trace how proceeds are used and consult current Publication 936 or a qualified tax professional.
A HELOC is usually a junior lien. If you later refinance the first mortgage, the HELOC lender may need to subordinate its lien. The CFPB warns that the HELOC lender can refuse, potentially requiring the line to be paid off before refinancing. Ask about subordination policy before opening a large line.
A cash-out refinance removes the old first mortgage at closing and creates a new lien. Existing junior liens may need payoff or approved subordination. Property liens, title defects and appraisal problems can delay either transaction.
How to compare real HELOC and refinance offers
Define the same cash need
Compare both options using the same net amount after closing costs, payoffs and required reserves.
Record the old mortgage
Note balance, rate, remaining term, payment, prepayment terms and projected payoff date.
Collect written offers
For the HELOC, capture index, margin, cap, fees and payment rules. For refinancing, compare Loan Estimates with consistent lock timing.
Calculate multiple horizons
Compare upfront cost, payment, balance and interest after three, five, ten years and the expected ownership period.
Stress-test and verify
Model HELOC rate increases, confirm credit-score/LTV assumptions and ask about fixed conversion, subordination and early closure.
APR alone does not solve the comparison because the products have different balances, terms and draw behavior. Use a spreadsheet or amortization calculator that preserves the old mortgage separately under the HELOC path.
Frequently asked questions
Is a HELOC cheaper than a cash-out refinance?
It can be when the old mortgage has a low rate and the cash need is modest, but variable rates and repayment terms can change the result. Compare total costs under stated assumptions.
Which requires a higher credit score?
There is no universal answer. HELOC lenders set thresholds, while cash-out rules depend on agency, automated findings, LTV, property and lender overlays.
Does a HELOC replace my mortgage?
Usually no. It is typically a second, junior lien with a separate payment while the first mortgage remains in place.
Does cash-out refinancing change my whole mortgage rate?
Yes. It pays off the old mortgage and creates a larger new mortgage, so the new rate applies to the entire new principal balance.
Can a HELOC rate increase?
Yes. Most HELOCs are variable-rate lines tied to an index plus a margin. Review the floor, adjustment rules and lifetime cap.
Which has higher closing costs?
Cash-out refinancing often has higher upfront mortgage-closing costs, but HELOCs can have appraisal, annual, early-closure or other fees. Compare written disclosures.
Can I use either option for debt consolidation?
Yes, but doing so converts unsecured debt into debt secured by the home. Compare total cost and prevent new card balances.
Is the interest tax-deductible?
Potentially when proceeds are used to buy, build or substantially improve the qualifying home, subject to IRS rules and limits. Personal use generally does not qualify.
Can I refinance later if I have a HELOC?
Possibly, but the HELOC lender may need to approve subordination and can refuse. Payoff of the line may be required.
Which is better for renovations?
A HELOC can suit staged invoices; cash-out refinancing can suit one known large budget when replacing the old mortgage is economically sensible.
Does cash-out refinancing restart the loan term?
A new term begins. Choosing 30 years can reduce the payment while extending debt and increasing lifetime interest. Shorter terms may be available.
Can either option guarantee savings?
No. Rates, fees, property value, repayment behavior and holding period determine cost. Compare real offers and stress-tested scenarios.
Bottom line
Choose a HELOC when preserving the existing mortgage and drawing only what is needed outweigh variable-rate and second-lien risks. Choose a cash-out refinance when replacing the full mortgage produces a genuinely competitive fixed structure after closing costs and term extension are counted.
The old mortgage is the center of the comparison. Never compare only the HELOC rate with the refinance rate; compare both complete debt paths over the same period.
2 thoughts on “HELOC vs. Cash-Out Refinance: Which Is Better in 2026?”
Comments are closed.